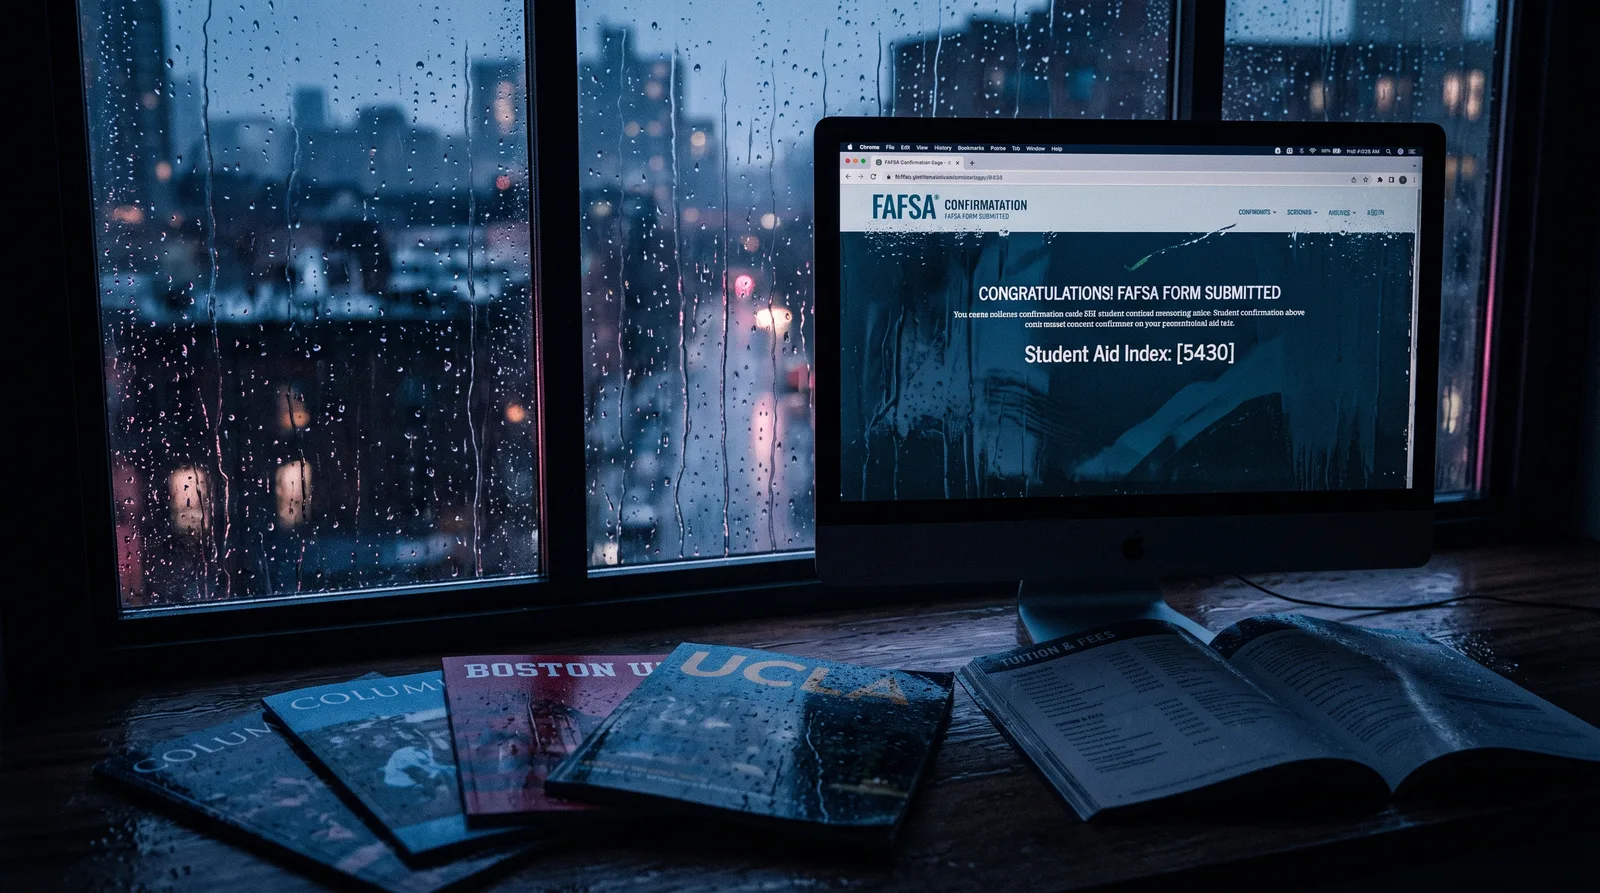
Most families fixate on a college's sticker price — but the number that actually determines what you'll pay is hiding inside your FAFSA. It used to be called the Expected Family Contribution, or EFC. It's now called the Student Aid Index (SAI). The name changed; the power didn't. Understanding it changes everything about your college search.
From EFC to SAI
The rename was deliberate. "Expected Family Contribution" implied that's what your family would actually pay. It rarely was. The SAI is clearer about what it actually is: an index number colleges use to estimate your financial strength and calculate your need. It's a formula output, not a bill.
What the SAI actually measures
The SAI is calculated from your family's income, assets, family size, and number of family members in college. The formula treats parent assets and student assets differently — student assets are assessed more heavily, which is why money held in a student's name can hurt aid more than the same amount in a parent's name.
Why it's not what you pay
Here's the key insight: your SAI is not what you'll write a check for. A college's Cost of Attendance minus your SAI equals your financial need — but colleges don't always meet 100% of need, and they meet it with a mix of grants, loans, and work-study. Two schools can produce the same SAI and hand you very different actual costs.
How colleges use it
Colleges use your SAI to determine eligibility for federal, state, and institutional aid. Need-based grants, subsidized loans, work-study, and even some merit scholarships use SAI as a gate or a factor. A lower SAI opens more doors; a higher SAI doesn't close all of them, but it shifts you toward merit-based aid rather than need-based aid.
What you can control
You can't change your income overnight, but you can influence the formula: understand which assets are assessed and which aren't (retirement accounts generally aren't), time large financial moves carefully, and file the FAFSA as early as possible — some aid is first-come, first-served. Most of all, don't let the sticker price scare you away from a school before you've filed and seen your actual SAI. The number that matters isn't on the brochure; it's on your Student Aid Report.
The Ultimate College Access Blueprint
Turn these notes into a structured, step-by-step practice — with progress tracking, assessments, and personalized guidance.
Explore the course
