


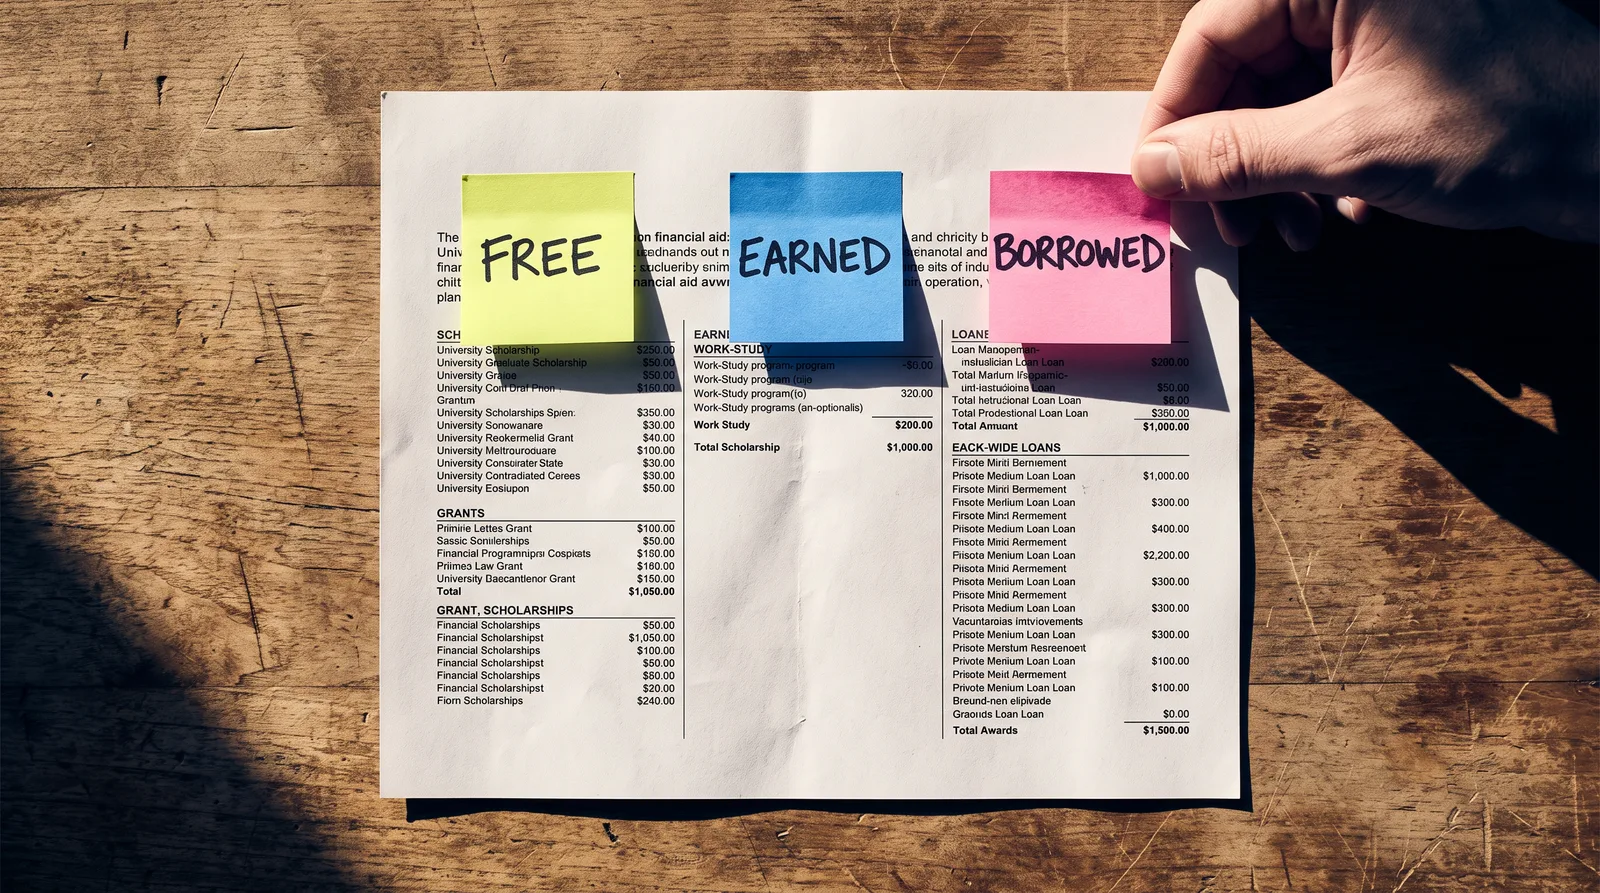
A college can look affordable on the first page of its financial aid offer and become far more expensive once you separate scholarships from loans, estimate living costs, and account for aid that may disappear after one year. To compare college financial aid offers well, your family needs more than the bolded total at the bottom of each letter. You need to know what is free, what must be repaid, what is earned through work, and what remains for your family to cover.
This is one of the most consequential financial decisions a student will make. A thoughtful comparison protects both opportunity and long-term stability.
Start With the Real Cost, Not the Award Total
Financial aid offers can be difficult to compare because colleges use different formats and labels. One school may present a $35,000 “aid package,” while another offers $28,000. That does not mean the first school is less expensive. Its larger package may include substantially more federal loans or work-study.
Begin with each college’s published cost of attendance. This estimate generally includes tuition and fees, housing and food, books, supplies, transportation, and personal expenses. Then subtract only gift aid: scholarships and grants that do not need to be repaid.
The result is your estimated net cost.
Cost of attendance - grants and scholarships = estimated net cost
Do not subtract loans or work-study from your net cost as though they were discounts. Loans create future repayment obligations. Work-study is an opportunity to earn wages, not money automatically credited to the bill. A student must secure an eligible job and work the hours to receive those funds.
Also separate billed costs from indirect costs. Tuition, fees, housing, and meal plans may appear on the college bill. Transportation, books, winter clothing, off-campus groceries, and personal expenses may not. A school with a lower billed amount can still be costly if it is far from home or located in a high-cost area.
Build a Side-by-Side Financial Aid Comparison
Put every offer into the same simple format. A spreadsheet, notebook, or printed worksheet can work well, as long as each college is evaluated using the same categories.
For each offer, record the college’s cost of attendance, then list grants and scholarships separately from federal work-study, federal student loans, private loans, and any parent borrowing option. Finally, calculate the amount your family would need to pay from savings, current income, outside scholarships, or borrowing.
Your comparison should answer four practical questions:
- How much is truly free money?
- How much debt would the student need to take on each year?
- How much would parents or family members need to contribute or borrow?
- What is the likely four-year cost if the aid remains the same?
That last question changes the conversation. A $4,000 annual difference is not just $4,000. Over four years, it is $16,000 before tuition increases, loan interest, or changes in family finances.
Identify Gift Aid Carefully
Grants and scholarships are the strongest parts of an aid offer because they reduce the price without creating repayment. Yet families should still read the terms closely.
Ask whether each award is renewable, whether it requires full-time enrollment, and whether the student must maintain a particular GPA. A merit scholarship that requires a 3.5 GPA can be an excellent opportunity for a student with a strong academic record. It may be a financial risk, however, if the college’s grading culture or the student’s intended major makes that benchmark difficult to maintain.
Find out whether the dollar amount is fixed or rises with tuition. A $10,000 scholarship that remains flat for four years loses purchasing power if tuition increases annually. Need-based grants may also change if family income, assets, household size, or the number of siblings in college changes.
Treat Loans as Financing, Not Aid
Federal Direct Loans are commonly included in college offers. They can be useful, especially because federal loans typically have more borrower protections than private loans. But they are still debt.
For dependent undergraduate students, annual federal Direct Loan limits are generally lower in the first years of college and increase modestly later. If an offer assumes large Parent PLUS Loans or private loans to close the gap, pause before treating the college as affordable. Those loans often place the financial burden on parents, may require a credit review, and can carry significant long-term costs.
A manageable loan amount depends on the student’s likely career path, expected graduation timeline, and whether graduate or professional school may follow. A future physician, attorney, educator, artist, engineer, or entrepreneur may each face very different income patterns and additional education costs. There is no single “safe” number for every family. There is, however, a clear principle: do not let an acceptance letter pressure you into debt you have not fully calculated.
Look Beyond the First Year
An offer is only as valuable as its ability to support graduation. Before making a deposit, ask the financial aid office whether institutional scholarships are renewable for four years and what percentage of students retain them.
You should also review the college’s graduation rate, typical time to degree, and academic support resources. A lower-priced college that helps a student graduate on time may offer greater value than a school with a larger first-year award but higher transfer, withdrawal, or delayed-graduation risk.
Housing deserves attention, too. Some colleges provide affordable campus housing only in the first year, then expect students to compete for expensive off-campus apartments. Others require students to live on campus for multiple years. Compare the housing policy and realistic local rental costs before assuming later years will look like freshman year.
If a student is considering a program with required unpaid clinical hours, internships, student teaching, or intensive lab work, factor in how those commitments could limit paid employment. A plan that depends on substantial work hours may not be realistic every semester.
Know When to Ask for More Aid
An aid offer is not always final. If your family’s financial circumstances have changed since filing the FAFSA or CSS Profile, contact the financial aid office promptly. Job loss, reduced work hours, major medical expenses, divorce, death in the family, or unusual one-time income can justify a professional judgment review.
You may also ask whether the college can reconsider its offer based on a stronger package from a comparable institution. This is often called an aid appeal or reconsideration request. Be respectful, specific, and documented. State the gap, explain why it prevents enrollment, and provide the competing offer if requested.
An appeal is not a demand, and colleges are not obligated to adjust aid. Still, a well-prepared request can lead to additional grant funding, a corrected calculation, or clearer guidance about options. Submit it before enrollment deadlines, and keep copies of every document and communication.
Compare College Financial Aid Offers With Your Family’s Full Budget
The strongest choice is not automatically the college with the lowest number or the highest-ranked name. It is the institution where the student can thrive academically, persist through graduation, and leave with a financial plan the family can honor.
Talk openly about what family members can contribute each year without sacrificing rent, retirement savings, emergency reserves, or obligations to other children. If a parent plans to borrow, identify the exact loan, interest rate, monthly payment estimate, and repayment timeline. If the student plans to work, identify how many hours are realistic alongside classes.
Mikael Davis Academy’s evidence-based approach to college access is built around this kind of clarity: understanding the numbers before they limit a student’s choices. With more than 30 years of experience and $38 million-plus in aid secured, the central lesson remains practical: financial aid strategy works best when families act early, ask informed questions, and document every decision.
A college decision can carry pride, emotion, and urgency. Give the financial side the same careful attention you gave applications. The right offer is the one that supports a student’s goals without asking the family to ignore the true cost of getting there.