


A student can earn admission to a dream college and still face a difficult decision if the aid offer leaves a large gap. That is why learning how to apply for college financial aid is not a single form-filling task. It is a family financial strategy that begins before applications are submitted and continues until you compare final award offers.
For more than 30 years, Mikael Davis has helped students and families pursue educational opportunity with a structured, evidence-based approach. The same principle applies here: complete each step accurately, meet every deadline, and treat financial aid as something you actively manage rather than passively receive.
How to Apply for College Financial Aid: Start With a Calendar
Financial aid deadlines are often earlier than families expect. A college may have one deadline for admission, another for institutional scholarships, and another for need-based aid. State grant programs can have their own dates and may run out of funding. Missing a priority deadline can reduce the aid available to you, even if you eventually submit all required forms.
Create one calendar that includes the FAFSA opening date for your application year, each college's priority financial-aid deadline, state-aid deadlines, scholarship deadlines, and dates for submitting follow-up documents. Do not assume every school uses the same process. Some institutions require the CSS Profile or their own financial-aid form in addition to the FAFSA.
Students and parents should also create their federal StudentAid.gov accounts before sitting down to file. The FAFSA uses a contributor process, meaning a parent, spouse, or student may need to provide consent and complete their own portion. Getting accounts set up early prevents a last-minute login problem from becoming a missed deadline.
Complete the FAFSA Carefully, Not Quickly
The Free Application for Federal Student Aid, or FAFSA, determines eligibility for federal grants, work-study, and federal student loans. Colleges and states also use FAFSA information to award many forms of need-based aid.
Gather the information you will need before opening the application. This usually includes Social Security numbers or eligible noncitizen documentation, prior-prior year federal tax information, records of current savings and investments, and details about untaxed income when applicable. Families whose financial circumstances have changed since the tax year used on the FAFSA should still submit the form using the requested information. They can later ask colleges to review their current situation.
Accuracy matters. Report assets that the form asks for, but do not confuse regular household items with reportable investments. Retirement accounts and the value of the family home are generally handled differently from cash savings or nonretirement investments. If you are unsure how to answer a question, pause and verify before submitting. A rushed guess can create delays, corrections, or an inaccurate aid calculation.
Students should list every college they are seriously considering. You do not need an admission offer before sending FAFSA information to a school. Adding colleges early gives financial-aid offices time to prepare an offer after admission decisions are made.
Know When Other Forms Are Required
The FAFSA is essential, but it is not always sufficient. Many private colleges and some scholarship programs use the CSS Profile to understand a family's financial circumstances in greater detail. A college may also request an institutional aid application, tax returns, business records, or documentation related to a noncustodial parent.
This can feel intrusive, especially for families managing divorce, separation, small-business income, or a major financial change. Still, the additional questions often exist because colleges use their own methodology to distribute institutional funds. Completing them thoroughly can position a student for college-funded grants that FAFSA data alone does not capture.
Check each college's financial-aid checklist through its applicant portal. Do not rely only on the confirmation page after submitting the FAFSA or CSS Profile. A form can be received while a signature, consent, verification request, or supporting document remains outstanding.
Respond Quickly to Verification Requests
Some students are selected for verification, a process in which the college confirms information reported on the FAFSA. Selection does not mean you did anything wrong. It is a routine compliance step, but it does require prompt action.
Read each request carefully. Colleges may ask for tax documents, proof of identity, household details, or clarification of income and assets. Submit exactly what is requested and keep copies of every document. If a requested item does not reflect your family's current circumstances, contact the financial-aid office and explain the issue instead of sending incomplete paperwork.
Verification can delay an aid offer or prevent funds from disbursing if it remains unfinished. Treat every portal notification and email as time-sensitive, particularly during spring and summer when colleges are finalizing packages for incoming students.
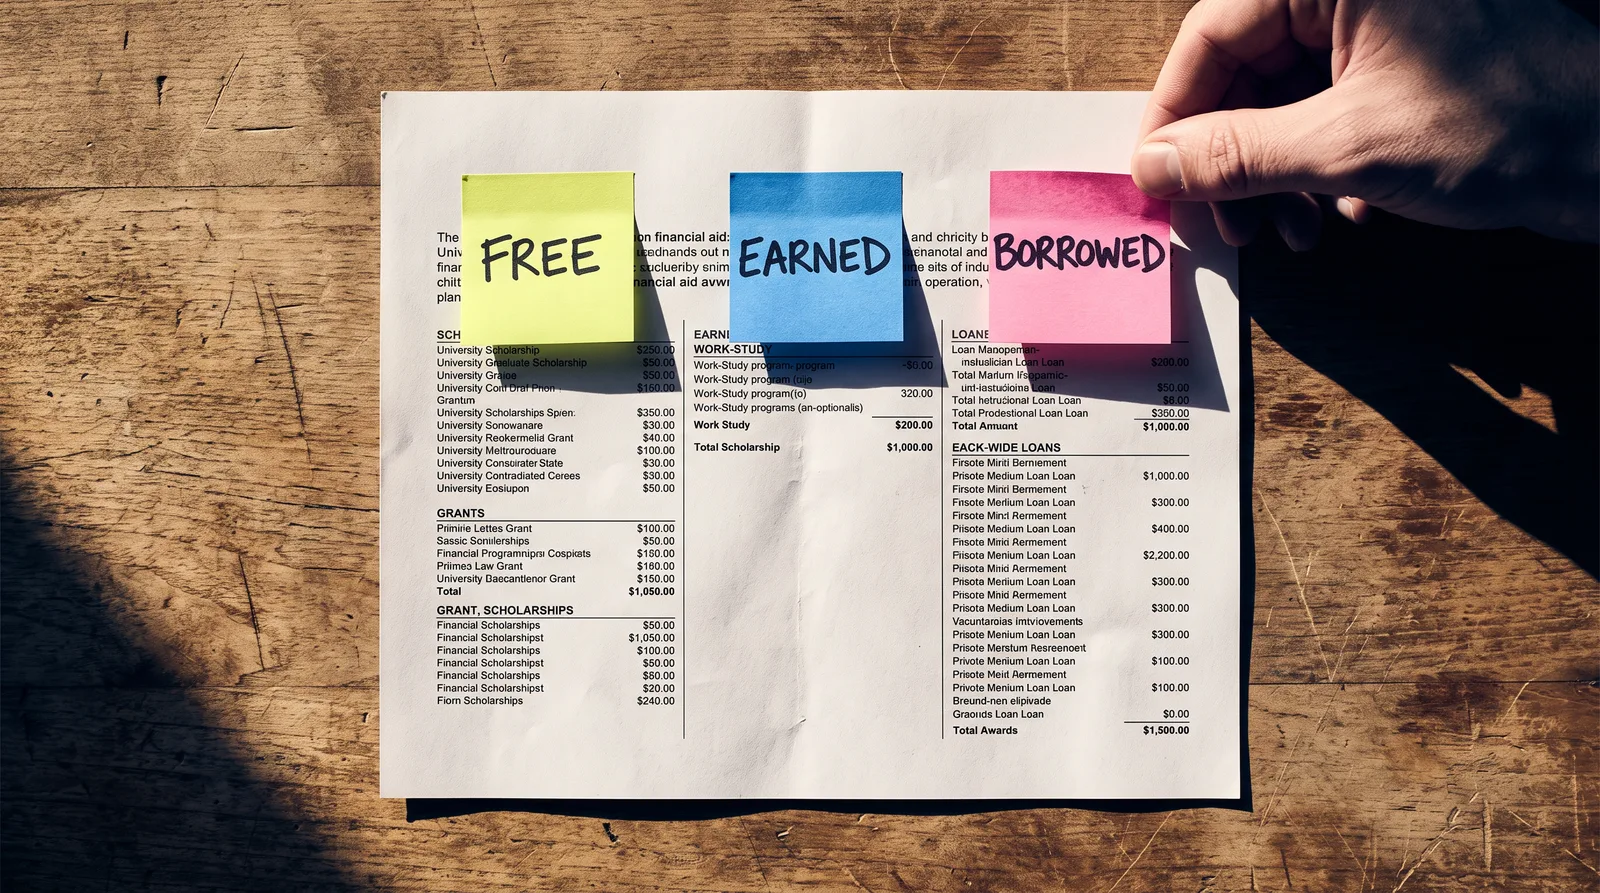
Separate Gift Aid From Borrowing
A financial-aid award letter can look generous at first glance because it may combine grants, scholarships, loans, and work-study into one total. These forms of aid are not equal.
Grants and scholarships are gift aid and generally do not need to be repaid, although they may have enrollment, academic-progress, or renewal requirements. Federal work-study is an opportunity to earn wages through eligible employment; it is not money automatically applied to your bill. Loans must be repaid, often with interest, and should be evaluated as a long-term obligation rather than a discount.
When comparing colleges, calculate the net cost for each school: the total cost of attendance minus grants and scholarships. Then look at what remains to be covered by family resources, earnings, and loans. Cost of attendance should include tuition, fees, housing, food, books, transportation, and personal expenses. A college with lower tuition is not automatically the less expensive choice if its grant support is weak or living costs are high.
Also review renewal terms. A first-year scholarship that requires a high GPA, full-time enrollment, or annual reapplication may not be as dependable as a renewable grant with clear conditions. Ask whether institutional aid is expected to continue in later years and whether tuition typically rises annually.
Ask for a Professional Judgment Review When Facts Change
The FAFSA uses tax information from an earlier period, which may not reflect a family's present ability to pay. Job loss, reduced hours, divorce, death in the family, high unreimbursed medical expenses, natural disasters, or the loss of one-time income can materially change the picture.
In these situations, contact each college's financial-aid office and request information about a professional judgment review, sometimes called a special-circumstances appeal. Be factual and specific. Explain what changed, when it changed, and how it affects your household now. Provide documentation, such as termination notices, recent pay stubs, medical bills, or evidence of changed benefits, when requested.
An appeal is not a demand for more money, and a positive outcome is never guaranteed. Colleges have limited budgets and their own policies. But families should not assume that FAFSA results are the final word when their financial reality has changed substantially. A well-documented request gives the aid office information it may need to reassess eligibility.
Build a Plan Before You Accept the Offer
Once award letters arrive, place them side by side and use the same categories for every college. Focus on net cost, gift aid, loan amounts, work expectations, renewal rules, and any remaining gap. If a parent loan or private loan is part of the plan, estimate what repayment could mean for the household after graduation.
This is also the moment to distinguish between the college you prefer and the college you can afford without creating unnecessary financial strain. The best choice depends on the academic program, career outcomes, support services, distance from home, and the realistic four-year cost. Families should make that decision with complete numbers, not assumptions.
For students who want structured support, the Show Me The Money pathway at Mikael Davis Academy can help turn scattered financial-aid tasks into an organized strategy. The goal is not simply to submit forms. It is to preserve options, reduce avoidable borrowing, and make a college decision that supports both achievement and affordability.
Your financial-aid application is one of the first major financial decisions connected to your education. Give it the same attention you would give an admission application: begin early, document carefully, ask informed questions, and keep advocating for the opportunity you have earned.

